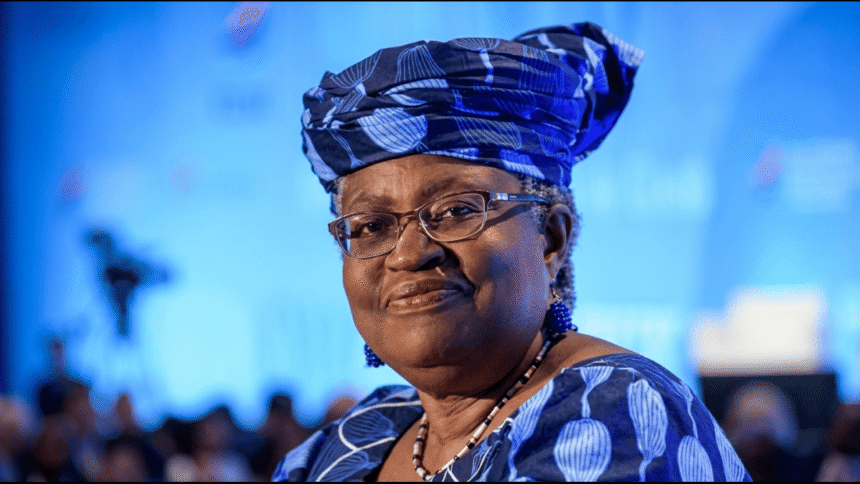
WTO Director-General Ngozi Okonjo-Iweala urges Nigeria to sustain economic reforms and manage debt cautiously at the 7th Africa Emerging Markets Forum in Abuja.
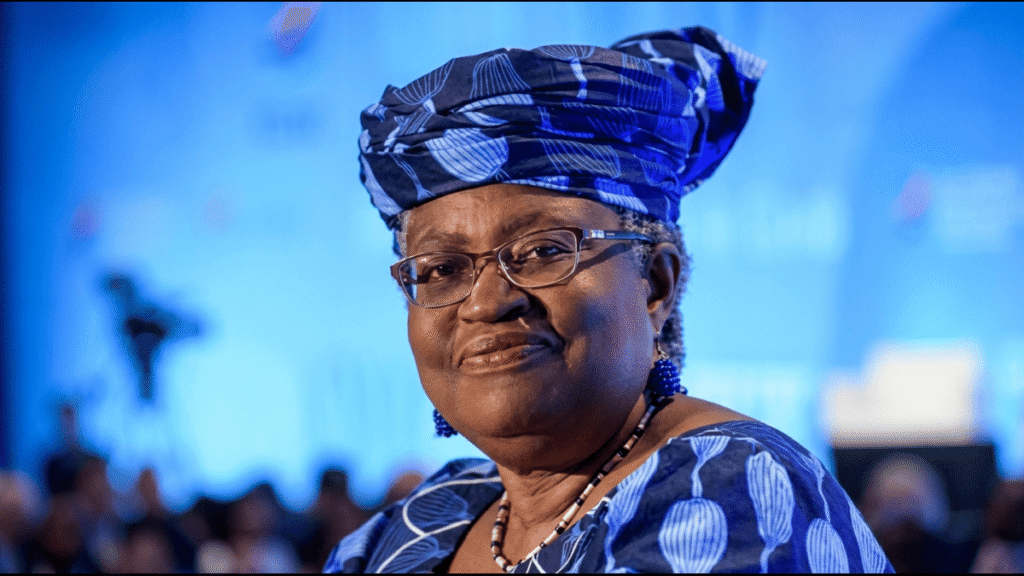
World Trade Organization Director-General Dr. Ngozi Okonjo-Iweala called on Nigeria to press ahead with macroeconomic reforms, exercise caution on debt contracting, and ensure ordinary citizens feel the benefits of fiscal adjustments in the real economy.
Okonjo-Iweala spoke during a fireside conversation with Central Bank of Nigeria Governor Olayemi Cardoso at the 7th Africa Emerging Markets Forum in Abuja, organized by the CBN in collaboration with the Emerging Markets Forum and the Centre for the Study of the Economies of Africa.
The forum carried the theme Building Resilience Amidst Geoeconomic Uncertainties. Commending the CBN’s monetary and foreign exchange reforms, Okonjo-Iweala told the gathering that fiscal discipline must accompany every step of the reform process.
“Nigeria needs to continue the work on overall macroeconomic reforms with a careful approach to fiscal issues, contracting of debt, and debt management,” she stated. “Above all, Nigeria needs to focus on creating jobs and economic opportunities for a young and hungry population.”
She added: “Nigerians have to feel the dividends of reform in the real economy.” On global trade, the WTO chief disclosed that the value of goods and services traded worldwide reached a record $34.65 trillion in 2025, up seven percent from the preceding year.
Okonjo-Iweala argued that predictions of widespread trade fragmentation had not materialized. About 72 per cent of global goods trade still flowed under WTO rules, she told the forum, a figure she presented as evidence of the trading system’s continued relevance despite geopolitical tensions and policy uncertainty.
She urged African countries to capture opportunities arising from global supply chain diversification, especially in critical minerals, and to move beyond the extract-and-export model toward building regional value chains and processing industries.
“For Africa in particular, instead of the extract-and-export model, the goal should be higher value, higher productivity growth driven by the development of sub-regional value chains,” she said, warning the continent could miss a major opportunity if it failed to act promptly.
Cardoso, speaking at the same forum, said Africa must convert global disruptions into opportunities through stronger institutions, deeper regional integration, and greater investment in technology. He observed that intra-African trade still accounted for only about 16 percent of the continent’s total trade, a figure he called inadequate.
“For Africa and other emerging markets, the question is no longer whether the global order is changing, but how we turn that change from a source of vulnerability into a source of growth and shared prosperity,” Cardoso told delegates.
The CBN governor called for stronger regional value chains, improved transport infrastructure, harmonized customs systems, and faster cross-border payments under the African Continental Free Trade Area. He also urged African nations to rely more on domestic savings, pension funds, insurance assets, and diaspora capital to finance development.
World Bank Group Chief Economist and Senior Vice-President for Development Economics Indermit Gill delivered a keynote urging developing countries not to be distracted by fears surrounding artificial intelligence, arguing it presented greater opportunities than risks because it would complement rather than replace workers.
“If you’re a Nigerian, tune it out,” Gill said of pessimism surrounding AI. He advised developing countries to focus on adapting AI to local conditions rather than competing directly with advanced economies on frontier AI models and recommended prioritizing predictive AI for agriculture, healthcare, education, and judicial services.
CBN Deputy Governor for Corporate Services Dr. Muhammed Abdullahi disclosed that verified legacy foreign exchange obligations exceeding $7 billion had been settled. Gross external reserves reached $52.52bn as of July 17, while net usable reserves recovered to more than $43bn, he confirmed.
Abdullahi told delegates that non-oil exports had risen 38.7 per cent year-on-year and monthly portfolio investment inflows had climbed from $0.33bn in January 2023 to more than $2bn by January 2025. “Nigeria’s experience shows that recovery is possible when difficult reforms are backed by consistent and disciplined policy,” he stated.
Emerging Markets Forum Founding Director and Chief Executive Harinder Kohli described Africa as the world’s “ultimate frontier for economic development.” The Abuja meeting was the seventh edition of the forum and the largest in the organization’s history, drawing policymakers, academics, central bankers, and development experts to discuss monetary policy, artificial intelligence, urbanization, investment, and Nigeria’s sustained push to sustain economic reforms and manage debt cautiously.